


Premium brands have always sold more than products. They sell origin, craft, scarcity, durability and trust. In high-end consumer goods, the story behind a product is part of the product itself. A leather bag, a watch strap, a pair of shoes or a luxury accessory carries value because customers believe in the quality of what they cannot always see. That belief is now being tested and the test begins in the supply chain.
The Premium Promise Now Depends on Upstream Proof
Sustainability expectations in premium goods are no longer limited to brand-owned stores, packaging choices or annual ESG disclosures. The pressure has moved upstream, into the material base of the industry. For companies dependent on leather, textiles, metals, gemstones, packaging and specialty ingredients, the hard questions increasingly sit with suppliers and the answers must be verifiable.
High-end consumer goods occupy a distinct position in the sustainability transition. Compared with mass-market categories, premium brands often have stronger margins, greater pricing power and more influence over consumer expectations. That gives them the ability to absorb early transition costs, test better materials, support supplier upgrades and set standards that later influence the wider market.
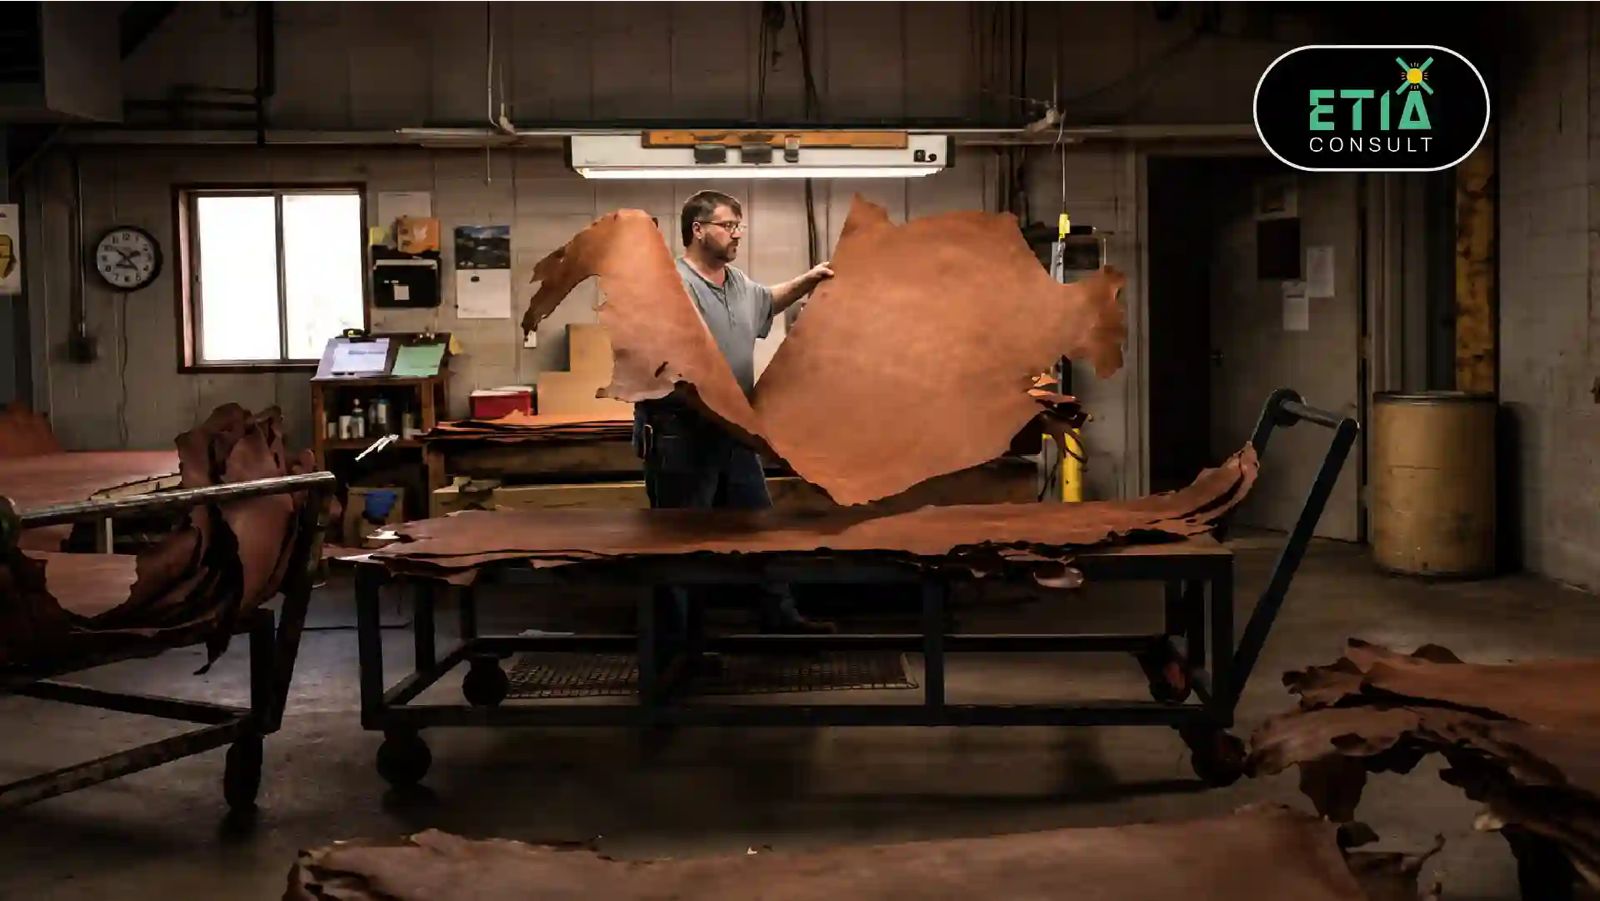
That advantage only matters if it is backed by operational visibility. The environmental and social footprint of premium products is often concentrated outside the brand’s own walls and in leather goods, it begins with the hide, not the handbag.
The brand may design, market and retail the final product, but the real sustainability profile begins much earlier with animal origin, hide collection, tanning, chemical use, water treatment, energy consumption, logistics and manufacturing. Each stage produces data. Each stage also introduces uncertainty. This is where ETIAconsult helps organisations build a connected picture of what is actually happening upstream.
The Leather Supply Chain: Where Data Actually Lives
Leather is one of the most important materials in luxury and premium goods. It is also one of the most difficult to manage from a sustainability data perspective. Understanding where the data challenge sits requires understanding each stage of the value chain.
Tanneries sit at the most critical and most data-intensive point in this chain. That process can involve significant water use, chemicals, energy, waste and wastewater treatment requirements. For brands, this means tannery performance is not simply a supplier management issue it directly affects Scope 3 emissions, nature-related risk, chemical safety, product traceability and customer-facing credibility.
Many brands have supplier codes, certification requirements and audit processes in place but these mechanisms often operate as separate layers. One system tracks procurement. Another stores audit findings. Another collects emissions estimates. Sustainability teams are then left trying to convert scattered information into a coherent view of risk. That model is no longer adequate.
Tannery Data Is Becoming a Scope 3 Pressure Point
Scope 3 reporting depends on the ability to collect, validate and normalise supplier data at scale. For leather-heavy portfolios, this means understanding which tanneries are linked to which products, what emissions factors are being used, whether primary data is available, how supplier performance changes over time and where the largest intervention opportunities sit. Without that structure, companies end up reporting averages when they need insight.
The challenge is not that brands are unaware of this. The problem is that existing mechanisms supplier questionnaires, certifications, periodic audits often generate point-in-time snapshots, not the continuous, structured data that CSRD reporting and investor-grade sustainability management now require.
Scope 3 Category 1
Purchased goods and services the category that captures tannery and raw material emissions. For most luxury brands, this is the single largest emissions category and the hardest to measure accurately.
Nature-Related Risk
Tanning processes can generate significant water consumption and pollution risk. Brands with nature-related disclosure obligations under TCFD and emerging TNFD frameworks need facility-level data, not sector averages.
Chemical Safety
Restricted substance lists, REACH compliance, and consumer product safety rules require traceable chemical documentation from the tannery stage through to the finished product.
Product Traceability
Customers, retailers, and regulators increasingly expect brands to demonstrate where materials came from. Digital product passports are becoming a regulatory reality in the EU making origin data a commercial necessity.
Regulation Is Raising the Floor. Markets Are Raising the Ceiling.
Regulation is accelerating the shift from voluntary sustainability claims to value-chain accountability. CSRD is pushing companies to report more clearly on material impacts, risks and opportunities across their value chain. Due diligence expectations are also increasing around environmental and human rights risks the EU’s Corporate Sustainability Due Diligence Directive (CSDDD) will require companies to actively manage upstream harm, not just disclose it.
EU CSRD Value Chain Reporting
The Corporate Sustainability Reporting Directive requires companies to disclose material impacts, risks and opportunities including those in the upstream supply chain. For leather-heavy brands, this means tannery data is no longer optional. It is a reporting obligation.
CSDDD Active Due Diligence
The Corporate Sustainability Due Diligence Directive moves beyond disclosure to require brands to identify, prevent, and mitigate adverse environmental and human rights impacts across their supply chains including Tier 2 and Tier 3 suppliers that many brands currently cannot see.
Digital Product Passports
EU textile and leather regulations are moving toward mandatory product-level traceability meaning brands will need to demonstrate material origin, chemical compliance and sustainability credentials at SKU level, not just at the brand level.
Investor & Market Expectations
Financial institutions integrating ESG factors as required under UN PRI frameworks are asking harder questions about Scope 3, supplier risk and proof of responsible sourcing. Premium brands with weak supplier evidence face rising cost of capital, not just reputational exposure.
This matters because premium goods are built on trust. A mass-market brand may survive a degree of opacity. A premium brand has far less room to hide behind complexity. In that sense, supplier data is becoming part of what makes a product premium connecting directly to the principles ETIAconsult applies in Corporate Sustainability 2.0 strategy.
From Compliance Reporting to Supplier Intelligence
The next phase of sustainability in premium goods will not be won through broader claims or longer reports. It will be led by companies that can turn supplier data into business intelligence. That requires three fundamental shifts in how brands approach their upstream relationships.
From Static Questionnaires to Living Supplier Profiles
A tannery, packaging supplier or material processor should not be assessed once and then filed away. Its emissions, certifications, audit findings, energy mix, water performance and compliance exposure need to be visible over time continuously updated, not periodically refreshed. This is the foundation of credible ESG supply chain management.
From Equal Treatment to Risk-Weighted Prioritisation
Not every supplier requires the same level of engagement. The highest-emission, highest-risk and highest-volume suppliers should be identified clearly so sustainability and procurement teams can focus their effort, budget, and engagement capacity where it generates the most value. Generic supplier programmes spread resources too thin and miss the interventions that move the needle.
From Year-End Reports to Traceable Numbers
Every number used in Scope 3 calculations should have a clear source, assumption and audit trail. This is what separates credible sustainability management from year-end reporting theatre. It is also what external assurance providers and regulators will increasingly test. Aligned with best-practice sustainability reporting architecture, traceability is not a luxury it is the new baseline.
At ETIAconsult, we help organisations navigate this shift by combining sustainability advisory, data intelligence and implementation support. For companies in premium goods, fashion, leather and adjacent consumer sectors, the priority is clear: move from fragmented supplier information to a connected view of Scope 3 exposure, supplier performance and regulatory readiness.
The Opportunity Is Bigger Than Compliance
Better supplier data can do far more than satisfy a regulatory requirement. For premium goods companies willing to invest in genuine supply chain intelligence, the returns extend well beyond compliance:
- Identify decarbonisation levers supplier-level emissions data reveals which interventions will reduce Scope 3 most efficiently, rather than applying uniform pressure across all suppliers
- Strengthen supplier relationships data-driven engagement shifts conversations from compliance checklists to genuine performance partnerships
- Support product-level traceability building the data infrastructure for digital product passports before they become mandatory
- Reduce reporting risk auditability of Scope 3 numbers reduces the exposure associated with external assurance and regulatory scrutiny
- Protect the premium promise in a category where credibility is the product, weak supply chain evidence is a direct commercial threat
Premium brands have always understood the value of detail in design, material, craft and finishing. The next decade will test whether that attention to detail extends all the way into the supply chain. In high-end goods, traceability is no longer just a sustainability requirement. It is becoming part of the product’s value.
Companies that make this transition early will build a competitive advantage that is difficult to replicate. Supplier intelligence, once built, becomes a proprietary asset informing procurement decisions, supporting brand storytelling, and providing the regulatory readiness that late movers will scramble to achieve. This mirrors the approach ETIAconsult brings to agile transformation in complex, regulation-heavy sectors.
Frequently Asked Questions
Key questions on supplier data, leather supply chains, and Scope 3 reporting for premium goods brands
Turn Your Supplier Data Into
a Competitive Advantage
ETIAconsult helps premium goods, fashion, and leather brands build connected views of upstream sustainability exposure from tannery Scope 3 data to CSRD-ready reporting architecture.